100% Financing for Rural & Suburban Homes
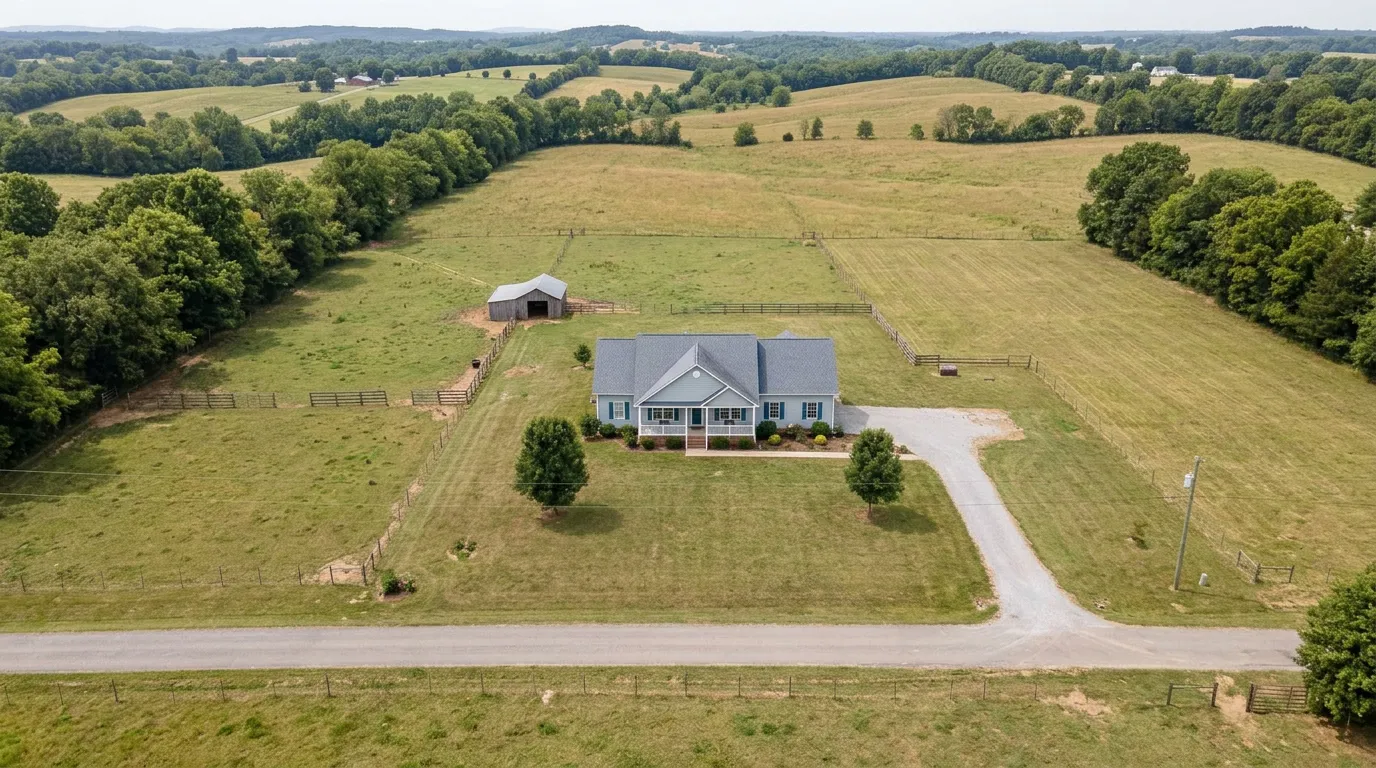
Not every path to homeownership runs through a big city and the USDA loan was built to reflect that. Designed for buyers purchasing in eligible rural and suburban areas, the USDA Rural Development loan offers 100% financing with no down payment required for those who meet income guidelines.
Things to Know
- 0%
- 620
- 1%
- 30 yr fixed
- By county
Ready to talk?
A loan officer who answers the phone, knows this program, and will tell you plainly whether it fits.
Disclaimer: Ark-La-TexFinancial Services, LLC d/b/a Benchmark Mortgage – NMLS ID #2143 (www.nmlsconsumeraccess.org) 5160 Tennyson Pkwy STE 1000, Plano, TX 75024. 972-398-7676. This advertisement is for general information purposes only, no guarantee is expressed or implied. Rates, terms, programs and underwriting policies subject to change without notice. This is not an offer to extend credit or a commitment to lend. All loans subject to underwriting approval. Not all applicants will qualify. Some products may not be available in all states and restrictions apply. (https://benchmark.us)
How USDA eligibility maps work
USDA eligibility is determined by the property’s address, not by how “rural” it feels. Many suburban areas just outside metro boundaries qualify. We'll check the address before you fall in love with the house.
Household income limits, explained
USDA looks at total household income, including people who will live in the home but aren’t on the loan. Limits vary by county and household size, and some deductions apply. It’s a different calculation than other programs, and it trips people up — we’ll run it early.
Guarantee fee vs. PMI
USDA charges an upfront guarantee fee (financed into the loan) and a small annual fee paid monthly. Both are typically lower than FHA mortgage insurance, which is part of why USDA payments are so competitive.
Property requirements
The home must be your primary residence, in an eligible area, and meet basic condition standards. Modest acreage is fine; income-producing farmland is not.
USDA vs. FHA vs. VA
All three help buyers with little cash. VA is for those who served. FHA works anywhere but carries lifetime mortgage insurance. USDA offers 0% down with cheaper insurance — if the address and income fit.
What makes it work for you?
- 100% financing — no down payment required
- Minimum credit score 620; no-score scenarios reviewed case by case
- Income limits based on total household income
- Property must be in a USDA-eligible rural or suburban area
- Low upfront and annual guarantee fees
- 30-year fixed-rate terms
A good fit if you…
- Are buying in a USDA-eligible rural or suburban area
- Have moderate household income within your county’s limit
- Don’t have savings for a down payment
- Want lower mortgage insurance costs than FHA
Probably not the right fit if you...
- Have household income above your county’s limit
- Are buying inside a major metro area that isn’t USDA-eligible
- Are buying a second home or investment property
Additional options to think about
Compare with other programs
FAQ
Short, honest answers. Your loan officer can go deeper on any of these.
Do I need a 20% down payment to buy a home?
No. Many buyers put down less, depending on the loan program. There are several options designed to make homeownership more accessible — including FHA (3.5% down), VA and USDA (0% for those who qualify), and conventional loans with as little as 3% down for first-time buyers.
How do I know if my area is USDA-eligible?
Eligibility is set by the USDA at the property-address level, and many suburban areas qualify. We check the address before you fall in love with the house.
Do USDA income limits count everyone in the household?
Yes. USDA income limits are based on total household income — everyone who will live in the home, even if they aren’t on the loan. Limits vary by county and household size.
What is the USDA guarantee fee?
USDA charges an upfront guarantee fee (financed into the loan) and a small annual fee paid monthly. Both are typically lower than FHA mortgage insurance.
FHA or conventional — which is better for me?
FHA is usually the better fit with lower credit scores or a smaller down payment, because its mortgage insurance doesn’t price up as sharply. Conventional usually wins with strong credit because PMI can be removed later. We’ll run both side by side.
HOW IT WORKS
Four steps from here to keys
Check the address and income limits
A 15-minute conversation about where you are and where you want to go.
Get pre-approved
You provide supporting documents like income statements, W-2s, and bank statements. Most of it can be uploaded in minutes.
Shop with confidence
We handle the appraisal and the paperwork sellers worry about.
Sign & Close
Sign, fund, and get the keys. We stay on the file until the end.
Check the address and income limits
A 15-minute conversation. No obligation. Real answers from a loan officer who answers the phone.